Dubai
The deepest, most liquid beachfront market — and the only one in a clear correction.
What happened. The regional conflict from late February 2026 hit tourism, transactions (Q3 sales value −47% YoY, Cavendish Maxwell) and sentiment. Prices have corrected 5–10% across most indices, with apartments falling faster than villas and beach areas most exposed to short lets (JBR, Marina) hit hardest.
What held up. Prime and ultra-prime: a record 165 sales above US$10M in Q1 2026, and Palm Jumeirah, Palm Jebel Ali, Bluewaters and La Mer remained among the most resilient. Beachfront land is finite, and the premium for being on the water has widened, not narrowed.
Supply. Dubai expects 75–85k handovers in 2026 (Savills). On the beach, about 35,000 units are under construction (Investment Map), concentrated in Dubai Islands (13,700), Dubai Marina (6,300), Dubai Harbour / Emaar Beachfront (4,800) and Mina Rashid (4,200). La Mer, JBR and Bluewaters have almost none.
What it means for buyers. For a long-term buyer this is a buying window: discounted entry prices, motivated off-plan sellers (secondary off-plan trades 10–15% below original prices citywide, per Fortune, Jun 2026), and handovers in 2027–29 into what should be a recovered rental market. Short-let income should be treated cautiously until tourism fully returns.
Dubai: supply, sales and yields by area
DLD transaction data from Investment Map: how much is being built in each beach area, what is listed for sale, and the recorded growth and yields.
| Community | Units under construction | Projects | Supply pressure | Listed for sale | Sales (1 yr) | Avg AED/sqft | Resale price change | Rental yield |
|---|---|---|---|---|---|---|---|---|
| Dubai Islands | 94 | Very high | 12 | 5,390 | 2,700 | +16% | 3% | |
| Dubai Marina (beach-adjacent) | 10 | High | 7,377 | 2,687 | 2,130 | +9% | 6% | |
| Emaar Beachfront · Dubai Harbour | 9 | High | 701 | 720 | 3,850 | +1% | 5% | |
| Mina Rashid (Rashid Yachts & Marina) | 16 | High | 50 | 741 | 2,890 | +6% | 6% | |
| Palm Jumeirah | 18 | Medium | 2,439 | 1,373 | 3,640 | +4% | 6% | |
| Palm Jebel Ali | 4 | Medium | — | 409 | 3,510 | 0% | — | |
| Bluewaters Island | 1 | Low | 244 | 134 | 4,990 | +17% | 6% | |
| JBR — Jumeirah Beach Residence | 0 | None | 1,881 | 565 | 1,760 | +1% | 6% | |
| La Mer · Port de La Mer · Jumeirah 1Investment Map area: Port De La Mer | 0 | None | 399 | 145 | 2,960 | +2% | 6% | |
| Dubai Creek Harbour (not beachfront, for reference) | 14 | — | 2,434 | 4,121 | 2,550 | +5% | 6% |
Supply decides the next three years. Dubai Islands, Dubai Harbour (which includes Emaar Beachfront), Dubai Marina and Mina Rashid together have about 29,000 units under construction. Rents and resale prices there will be capped while that stock hands over. La Mer, JBR and Bluewaters have almost nothing coming, which protects rents and supports values.
Yields are proven, mostly. DLD-recorded yields are about 6% across Palm Jumeirah, Bluewaters, La Mer, Mina Rashid, JBR and Dubai Marina, and 5% in Dubai Harbour. Dubai Islands records only 3% so far. That is early data, but it is a warning against buying there on the developers' yield promises.
Growth was strongest where supply is thin or the area is new. Bluewaters (+17%) and Dubai Islands (+16%) led in the year to April 2026, then Dubai Marina (+9%) and Mina Rashid (+6%). Palm Jumeirah (+4%), Dubai Harbour (+1%), JBR (+1%) and Palm Jebel Ali (flat) were already slowing before the correction.
Most stock for sale is in the Marina. Dubai Marina has 7,377 units listed and JBR 1,881, so buyers there can negotiate hard. Dubai Islands (12 listed) and Mina Rashid (50) are mostly off-plan, so resale stock is thin.
Source: Investment Map (investmentmap.ai), DLD-based, 1-year view (Apr 2025–Apr 2026), read 18 Oct 2026. Resale price change is the change in median resale AED/sqft against the previous 12 months; yield is based on the most recent sale and rental contracts in the period; listed for sale is current listings. These figures end in April 2026, so they include only the first weeks of the 2026 correction; the price falls quoted elsewhere in this report (to Aug–Oct 2026) are more recent. Jumeirah Bay and Pearl Jumeirah are left out because they had 18 and 2 sales. Supply pressure is our judgement from the pipeline.
Palm Jumeirah


Capital growth
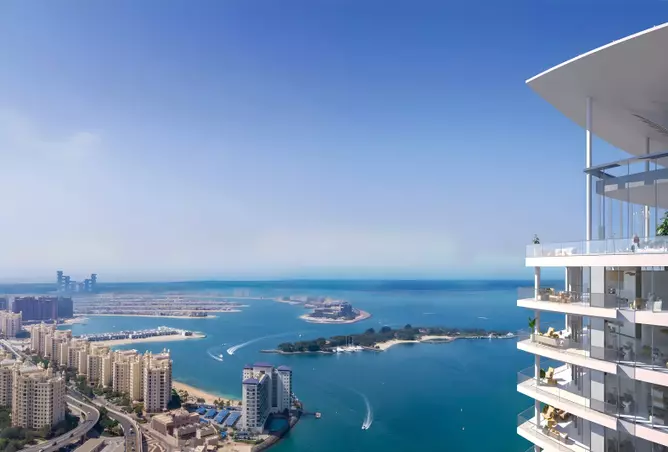
Dubai's trophy address: finite land, global recognition and the deepest US$10M+ market (50 such sales in H1 2026, second only to Dubai Hills). Apartment prices have corrected 5–9% this year, which is the entry point for a long hold.
Rental yield
Apartment gross yields of 5.1–5.4% (1BR rents ≈AED 145K, 2BR ≈AED 222K). Villas yield only 3.6–4%. Short-let premiums collapsed in March–August 2026 with tourism and are only now recovering.
Key projects
Shoreline, Serenia Residences, Oceana, Tiara, Ellington Beach House (2025), One at Palm (Omniyat)
Palm Beach Towers (Nakheel, from ≈AED 3.7M), Six Senses Residences (Select), Serenia Living (Palma), Orla Dorchester Collection (Omniyat), Como Residences (Nakheel, Q1 2027)
Ela (Omniyat, 2027), Olaia Residences (2027), The Alba Dorchester Collection (Omniyat, 2028), Maison Margiela Residences (2028), Passo by Beyond (2029), Trump International Tower (2031)
Watch: Prices currently falling (ValuStrat −8.6% YoY for apartments, Aug 2026); short-let and hotel exposure; averages swing with the luxury mix.
Bluewaters Island

Capital growth
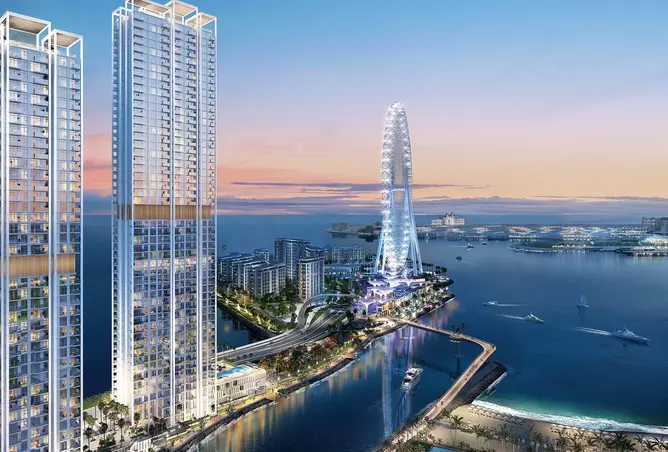
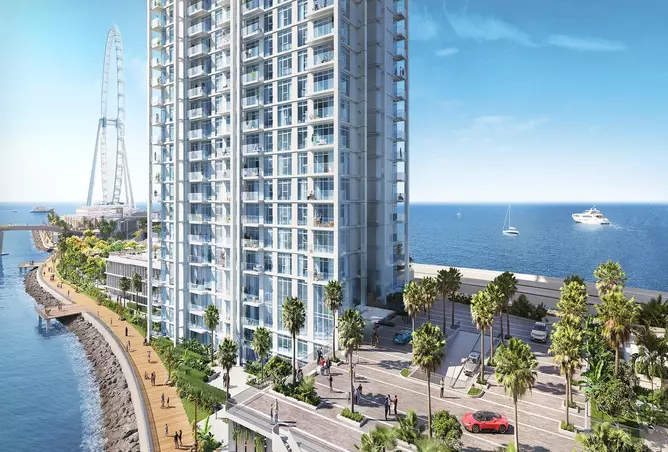
The most expensive beachfront apartments in Dubai, on a small island with almost no land left to build. It held its value better than any other beach area in H1 2026.
Rental yield
Gross yield of about 6.2% on a thin sample of deals. Rents are driven by premium long-let and serviced demand around Caesars / Banyan Tree and Ain Dubai.
Key projects
Bluewaters Residences (about 10 buildings and townhouses)
Bluewaters Bay (Meraas) — launched Feb 2023 from ≈AED 2.85–2.9M (1BR), handover Mar 2027, sold out
Watch: Very thin liquidity (65 resales in H1 2026), tourism-linked demand, highest entry price per sqft.
La Mer · Port de La Mer · Jumeirah 1


Capital growth
Freehold low-rise living on the beach in old Jumeirah, ten minutes from Downtown. It's one of the few beach areas still rising in 2026, and it set Dubai's top villa price this year (Dh350M, Jumeirah Asora Bay).
Rental yield
Gross yield of about 5.5%, with 1BR rents around AED 126K and 2BR around AED 206K. Rents held roughly flat this year while most of Dubai fell.
Key projects
Port de La Mer (La Cote, La Rive, La Voile and others), La Mer Sur Mer
Jumeirah Asora Bay (Meraas) — ultra-luxury, from ≈AED 45M, handover Q1 2029, sold out
Watch: Small, illiquid apartment market (resales fell 55% in H1 2026); limited new supply cuts both ways.
Emaar Beachfront · Dubai Harbour



Capital growth
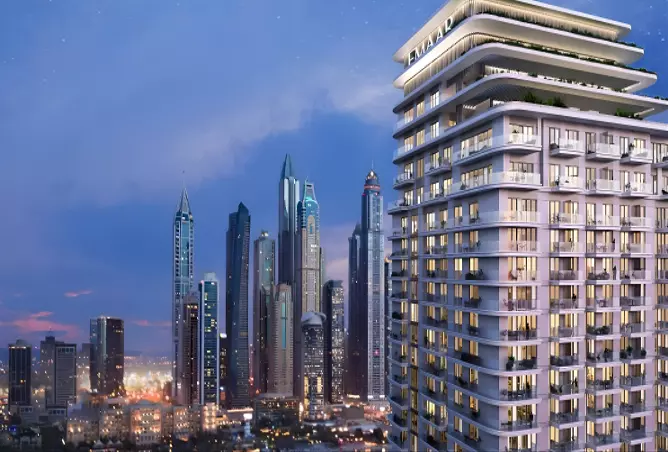
A private 1.5 km beach between the Marina and the Palm, delivered by Emaar. It is the most liquid new-build beach product. Prices are 7–12% down on a year ago as new towers hand over, which creates entry opportunities — off-plan resales are trading below the original price.
Rental yield
Gross yield of about 4.9% today. 1BR rents fell ≈16% this year to ≈AED 123K as new handovers added supply, so yields should recover as that stock is absorbed.
Key projects
Beach Vista, Sunrise Bay, Marina Vista, South Beach, Beach Isle, Grand Bleu (Elie Saab), Palace Beach Residence
Beachgate by Address (from ≈AED 3.0M), Address Residences The Bay
Seapoint (Q1–Q2 2028), Bayview by Address Resorts (Q3 2028), The Bristol (Q3 2029), plus in Dubai Harbour: Sobha Seahaven (≈2027), DAMAC Bay 1 & 2 by Cavalli (2027–28), The Residences at The Dubai Beach EDITION (2029)
Watch: Large handover wave to 2029 keeps rents and resale prices under pressure in the short term.
Palm Jebel Ali
Capital growth
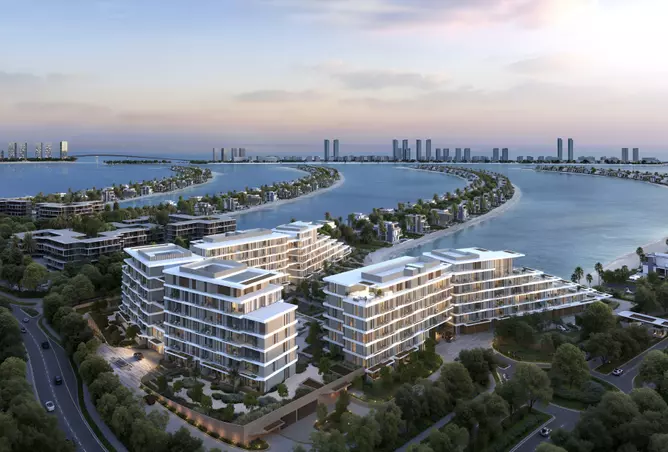
Twice the size of Palm Jumeirah, relaunched in 2023, with built villas priced around a third of the Palm Jumeirah equivalent per sqft. It had 40 sales above US$10M in H1 2026. This is the biggest long-term upside on the coast if delivery stays on track.
Rental yield
No rental history yet. The first villas hand over from late 2026, and the Palm Central apartments complete in September 2030.
Key projects
Beach and Coral Collections (Fronds K–P, finishing stage), Fronds A–F (2028), new Frond F release (Aug 2026)
Palm Central Private Residences (Nakheel) — 1BR from AED 2.7M, 2BR from AED 4.3M, completion Sep 2030
Watch: Long delivery horizon, distance from the city centre, and Nakheel's 2008 stall here; resale needs a Nakheel NOC.
Dubai Islands
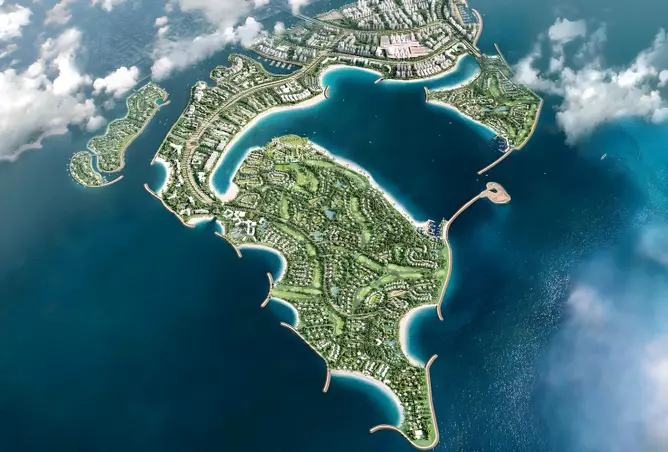

Capital growth
The cheapest way onto a real beach in Dubai, with about 20 km of public beaches, a bridge to the mainland and a new Bur Dubai bridge underway. It is a lower entry price than Palm Jumeirah or Emaar Beachfront, with growth as the community fills in.
Rental yield
Developers market 6–7.5%, but the few leases on record show about 3% (Investment Map, DLD). Treat developer yields as marketing until the 2027–28 handovers prove them.
Key projects
Rixos Beach Residences (Phase 2, Nov 2026), Beach Residences (Jan 2027), Bay Villas (636 villas and townhouses), Bay Grove Residences (Phase 4, Sep 2028, from AED 2.0M), Bay Estate (Cala, Agora, Verda; 2029–31, from AED 4.7M)
Ellington Cove (Jun 2028, sold out), Ellington Sands and Sands Phase 2 (Dec 2028, from AED 1.7M / 2.6M), The Meriva Collection on Dubai Islands B (Signature, Gardens, Shores, Sunset; Q2–Q4 2030, from AED 2.7M)
Siora district (≈2m sqft): Hado (Q2–Q3 2029, sold out), Hado Phase 2 (Sep 2029, from AED 2.16M), Siora (Dec 2029, from AED 2.4M), Shione (pre-launch)
JW Marriott Residences (CG Developers, Jan 2028, from AED 2.37M), Samana Ocean Pearl (Dec 2026), Imtiaz Beach Walk (the first completed building), Seacliff, Wynwood and Sunset Bay, The Bay Interiors by Missoni, Le Château Piétrus (Mr Eight), and 60+ smaller launches
Projects to watch

Ellington Cove
Two waterfront buildings with private beach access; launched Q4 2024.
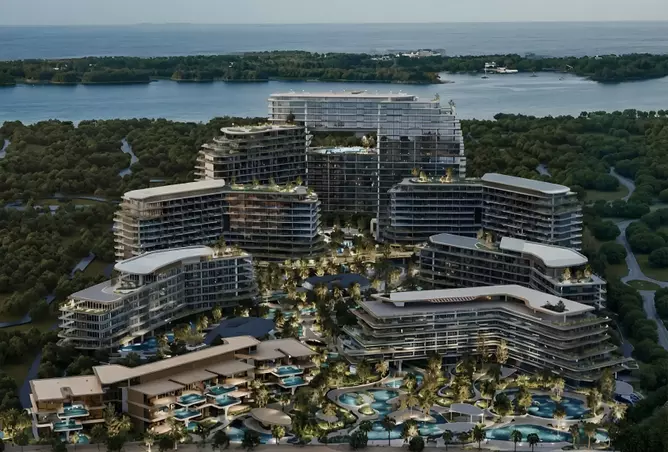
The Meriva Collection
Four buildings on Dubai Islands B (Signature, Gardens, Shores, Sunset), launched Feb–Apr 2026.
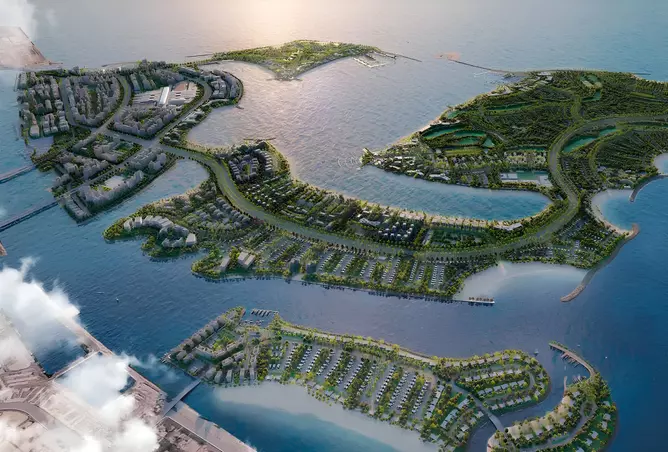
Ellington Sands
Beachfront low-rise; Phase 2 released Oct 2025.
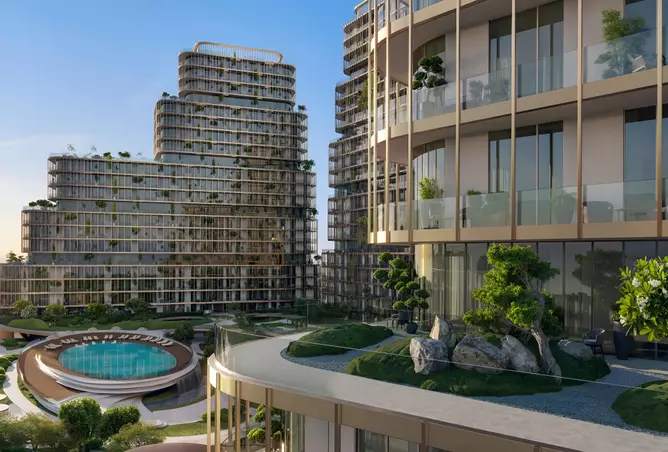
Hado by Beyond
First launch in Beyond's ≈2m sqft Siora beach district: three 21-floor towers, Japanese-inspired design; 1BRs 768–1,415 sqft.
Siora & Hado Phase 2
Follow-on Siora phases on the same beach; Shione is next.

Bay Grove Residences
Nakheel's own beachfront apartments; Phase 4 is the latest release.
Bay Estate
Nakheel's top-end beachfront collection (Cala, Agora, Verda), launched Mar 2026.
Rixos Beach Residences
Branded residences on a 700 m private beach next to the Rixos hotel; the first of the major branded projects due to hand over.
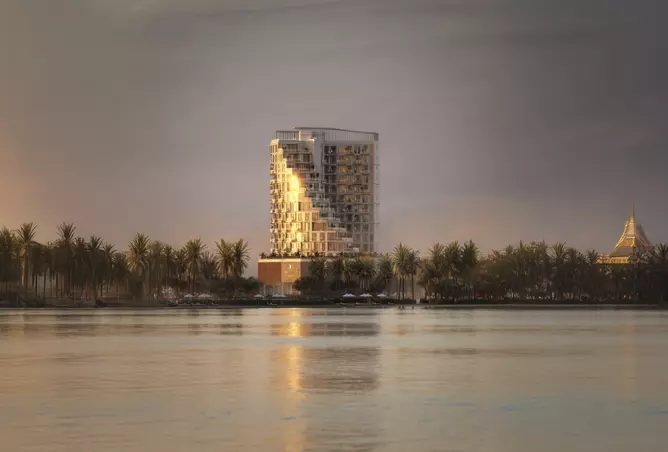
JW Marriott Residences
Branded tower with hotel management; a newer developer, so check its delivery record.
Launch and starting prices from developer and Property Finder project pages (Oct 2026); sold-out projects trade only as resales. Tier-1 names (Ellington, Beyond, Nakheel) are where we would focus on Dubai Islands.
Watch: Heaviest beach supply in Dubai (13,700+ units under construction across 94 projects, Investment Map) from many mid-tier developers; DLD-recorded yields only ≈3% so far; access depends on new bridges.
Mina Rashid (Rashid Yachts & Marina)


Capital growth
Emaar's marina community by the QE2 in old Dubai, with a small beach and a future Gold Line metro station (2032). It is the cheapest Emaar sea-facing entry.
Rental yield
DLD-recorded yields are about 6% on the existing towers (Investment Map). Seascape hands over in Q4 2026, which will give the first new-build benchmark.
Key projects
Sirdhana, Seagate, Clearpoint
Seascape (Q4 2026, from AED 1.5M), Marina Place (Q4 2028), SERA and BAYSTAR by VIDA (2029), AUREA and Fior (2030), Ellington Portside Square (Q4 2029)
Watch: Heavy pipeline to 2030 (4,200+ units under construction, Investment Map); the beach is small next to the Palm or Emaar Beachfront.
JBR — Jumeirah Beach Residence
Capital growth
Dubai's original beachfront: The Walk, The Beach and a deep rental pool. It has the highest gross yields of the beach communities.
Rental yield
Gross yield of about 6.5% (1BR ≈AED 108K, 2BR ≈AED 149K). Rents have held up better than prices this year.
Key projects
40 towers across Murjan, Sadaf, Bahar, Rimal, Amwaj and Shams (2007–08); Al Bateen (Al Ain Properties) is the main new addition
Watch: The weakest apartment prices in Dubai in 2026 (ValuStrat −16.9% YoY, Aug); ageing towers with high service charges; tourism-linked demand.
Dubai Marina (beach-adjacent)


Capital growth
The most liquid waterfront market in Dubai, with metro and tram and a short walk to JBR beach. It has the lowest entry price of the beach-adjacent areas.
Rental yield
Gross yield of about 6.1%, but rents are falling fastest here (Savills: −12.8% YoY, Q3 2026) as short-let investors switch to long lets.
Key projects
Marina Gate, Jumeirah Living Marina Gate, Vida Residences, LIV Residence, Marina Promenade and others
Six Senses Residences Marina (Select, Q3 2028, from ≈AED 5.8M), Liv Lux (Q4 2026), Aeternitas (2027)
Watch: Older stock; heavy short-let investor exposure driving rent falls.
Abu Dhabi
The most resilient market in 2026, with the lowest yields at the top end.
Abu Dhabi set records in H1 2026 and showed no Dubai-style correction, but the market has plateaued since March: Aldar's UAE sales fell 46% in H1, rents dipped 5% QoQ in Q2 (Cushman & Wakefield) and new rent increases are frozen. Foreigners can buy freehold in 50 designated investment zones. About 71,000 units are due by 2030, peaking in 2028.
Saadiyat Island
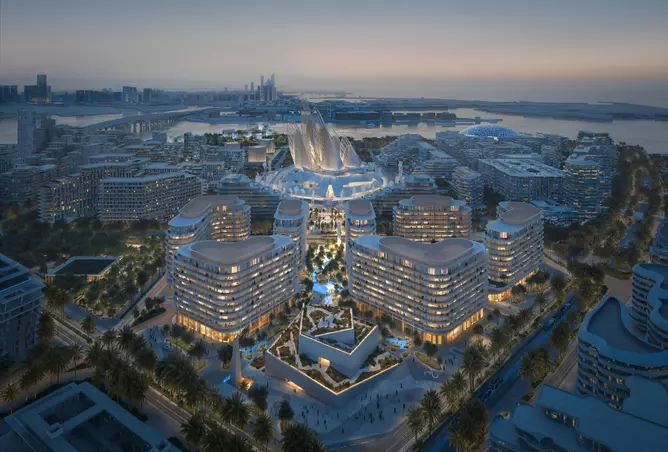

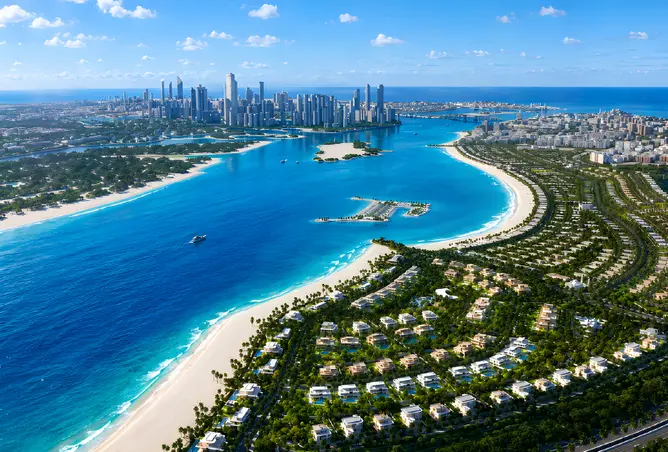
Capital growth
Abu Dhabi's scarcest and most expensive beach address, next to the Louvre and the Guggenheim (opening 11 December 2026), with Aldar's new 8 km Marsa Al Saadiyat masterplan to come. Transacted apartment prices rose 18–33% in the year to Q2 2026, but asking prices have been flat since Q1, so growth is levelling off at about AED 3,500–4,000/sqft.
Rental yield
The lowest yields in Abu Dhabi at about 3–4.5% gross (1BR rents ≈AED 133K against a 2026 median 1BR of AED 3.15M); prime Mamsha units are nearer 3%. Abu Dhabi has capped rent increases at 0% since June 2026, which limits uplifts on renewals.
Key projects
Louvre Abu Dhabi Residences, Mamsha Al Saadiyat, Saadiyat Beach Residences, Soho Square (Bloom), Manarat Living, The Grove
The Row Saadiyat (Aldar, Q1 2030, from AED 3.7M), Sei Saadiyat (Aldar, Q4 2030, from AED 2.95M), Mamsha Palm (Aldar, Q4 2028, from AED 3.6M), Nobu Residences (Q4 2027, sold out), The Arthouse (Q2 2028, sold out), Mandarin Oriental Residences (Sep 2028, from AED 6.2M), Four Seasons Private Residences (Al Ain Holding, Q3 2029, from AED 20.8M)
Talay at Marsa Al Saadiyat (Aldar, Q4 2029, from ≈AED 12.6M; with Yas Riva Reserve, over AED 5bn sold at launch)
Watch: Low yields; 85% of 2026 sales are off-plan; villa resale is soft (Saadiyat Lagoons asking −14.5% YoY); about 3,250 units under construction plus the Marsa Al Saadiyat pipeline.
Yas Island
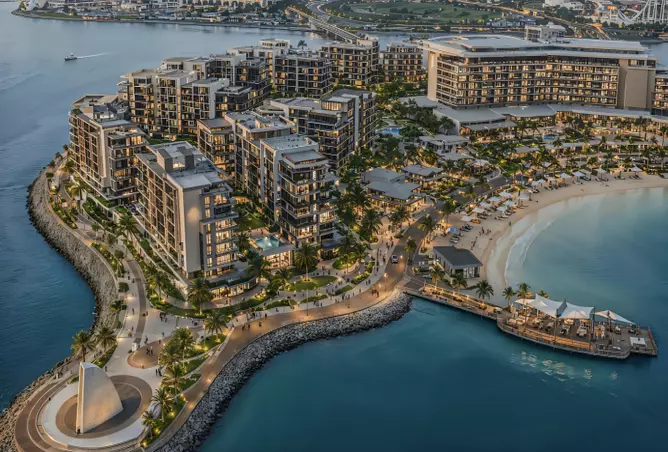
Capital growth
The events and leisure island (F1, the theme parks, Yas Bay) and the strongest mid-premium waterfront market in Abu Dhabi: apartment prices rose about 18% in the year to June 2026 (Knight Frank) and asking prices are up 41% over two years. Prices have levelled off since March, and the emirate's largest pipeline is here.
Rental yield
Gross yields of about 5.5–6% (1BR ≈AED 113K) and the fastest rent growth in Abu Dhabi (+18% YoY, Cavendish Maxwell H1 2026). Holiday-home income is exposed to the 14% fall in Abu Dhabi hotel guests this year.
Key projects
Sea La Vie, Mayan, Water's Edge, Ansam, Yas Beach Residences
The Canopies at Yas Point (Aldar, Q3 2030, from AED 1.65M), Yas Riva Residences (Aldar, Q4 2029, sold out), Yas Park Place (Aldar, Q1 2030, from AED 1.39M), Yas Living (Aldar, Q4 2028, from AED 980K), Stellar by Elie Saab (Emirates Developments, 2028, from AED 2.2M), Manchester City Yas Residences (Ohana, 2029), Sobha City (Q4 2029, from AED 5.09M)
Watch: About 7,700 units under construction — the largest pipeline in Abu Dhabi — which caps upside from 2027–28; the 0% rent cap on renewals.
Al Reem Island (waterfront)
Capital growth
The liquid, mid-tier core of Abu Dhabi and its busiest district by sales. Apartment prices rose 17–26% in the year to Q2 2026 and asking prices are still edging up, unlike Saadiyat and Yas. The Mid-Island Parkway (2027) is the next catalyst. It is a waterfront district rather than a true beach community.
Rental yield
About 6% gross (1BR ≈AED 94K on ≈AED 1.59M), the best of Abu Dhabi's waterfront hubs. Reem is reported to fall under ADGM rules and outside the 0% rent cap — confirm before relying on it.
Key projects
Riviera Residences (Mered, 2029–30, from AED 2.56M), Sunstone (IMKAN, Q4 2028, from AED 2.59M), Rotana Residences (Royal Group, Q4 2028, from AED 2.74M), Seamont Autograph Collection (Q4 2028, from AED 2.47M), Rixos Al Reem (Q3 2029, from AED 2.12M), Waterfront by Missoni (Emirates Developments, Q4 2029), Tara Park (Modon, 2029–30, from AED 1.64M)
Watch: Deep stock (about 27,500 investment-zone units) and many developers of mixed quality.
Al Raha Beach
Capital growth
An established beach and marina community between the airport and Yas, priced about 40–45% below Saadiyat per sqft and catching up: valuers recorded 17–24% apartment growth in the year to Q2 2026 (asking prices +5.5%). Yas and Etihad Rail are close by.
Rental yield
A solid 5.5–6.5% gross on ready stock (1BR ≈AED 111K), with little new supply inside the established precincts (Al Bandar, Al Zeina, Al Muneera).
Key projects
Al Bandar, Al Zeina, Al Muneera, Al Hadeel, Raha Lofts (Aldar)
Hilton Residences Al Raha (Emirates Developments, Q4 2028, from AED 2.5M), Baia (Reportage, Q2 2029, townhouses from AED 3.9M), Bab Al Qasr Seaview (Burtville, Q4 2029)
Watch: Ageing buildings and service charges; newer developers of mixed quality.
Hudayriyat Island
Capital growth
Abu Dhabi's hottest launch market: AED 19bn of sales in H1 2026 (27% of the emirate's residential sales). Hudayriyat Golf Estates sold about AED 13bn within days in July, and Bashayer phases sell out in a day. Apartment pricing (≈AED 2,200–2,500/sqft) is already at Yas levels.
Rental yield
No rental history — nothing has handed over yet. Modon's projected 6–8% yields are unverified.
Key projects
Bashayer Residences (Q1–Q2 2030, 1BR from AED 2.4M; phases 5 & 6 sold out in a day), Nawayef Park Views (Q1 2028, resale from AED 2.1M), Nawayef Village (Q1 2029), Hudayriyat Golf Estates (Q3 2030, from AED 4.25M), Al Naseem Villas (Q4 2026, sold out), Wadeem Gardens (Q2 2031)
Watch: Modon has no residential delivery record yet; concentrated speculative off-plan buying; no rental evidence.
Ramhan, Fahid & Jubail Islands · Al Jurf

Capital growth
Ultra-prime and villa islands: Ramhan (Eagle Hills, average sale ≈AED 15M), Fahid (Aldar, 6,000+ homes, AED 40bn+), Jubail (handovers since 2024; villas up about 40% YoY, Knight Frank) and Al Jurf near Ghantoot. These are capital plays rather than income plays.
Rental yield
No reliable rent or yield data yet; demand is holiday- and second-home-led.
Key projects
Ramhan Island (Q4 2026, sold out), Villas Phase 4 (Q3 2028, from AED 6.9M), The Bristol (Q4 2028, from AED 3.1M), Bvlgari Resort & Mansion (Q4 2030)
Fahid Beach Residences (Aldar, Q2 2029, from AED 3.5M, sold out); Bada Al Jubail (end-2027); AlJurf Gardens (ready), Jacob & Co Beachfront Living (Ohana, Q2 2028, from AED 1.5M)
Watch: Thin resale liquidity; about 3,550 units under construction on Fahid; confirm foreign freehold title in Al Jurf unit by unit.
Ras Al Khaimah
A Wynn-driven market with real upside and real timing risk.
RAK held up far better than Dubai in 2026 — annual growth stayed positive — but momentum stalled after February, asking prices are flat to slightly down over 12 months and Fitch has a negative outlook on the emirate. Ready stock trades at about AED 900–1,400/sqft and new branded off-plan at AED 2,500–4,800/sqft, so they are different products. Foreign freehold is limited to Al Marjan, Mina Al Arab, Al Hamra and Marjan Beach / RAK Central.
Al Marjan Island


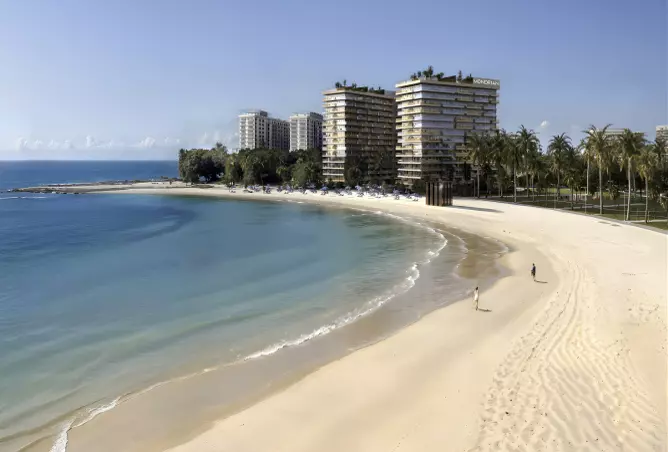
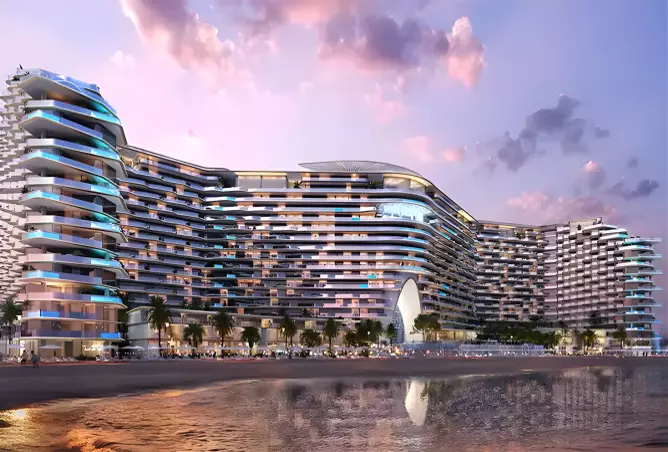
Capital growth
The purest play on Wynn Al Marjan Island, the UAE's only licensed gaming resort, now set to open in September 2027 (delayed from 2026; budget up to ≈US$5.7bn). Values rose 9–23% in the year to mid-2026 (ValuStrat, CBRE) but have been flat since Q1, and asking prices are up less than 1% in 12 months. Some early branded resales sit below launch price.
Rental yield
Ready 1BRs (≈AED 0.9–1.1M) let for about AED 52–59K, a 5–5.5% gross yield. Branded off-plan at AED 2,500–3,500/sqft yields only 2.5–3% on a long let and needs short-let or hotel-pool income, which won't step up until the Wynn opens; RAK hotel RevPAR fell 29% in H1 2026.
Key projects
Address Residences (Emaar, 2028, launched from ≈AED 1.74M), Nikki Beach Residences (Aldar, Q4 2028, sold out), Nobu Residences (H&H, Q1 2028, from AED 4.0M), Mondrian Residences (Elevate, Dec 2028, 1BR from AED 2.6M), Karl Lagerfeld Beach Residences (AARK, 2028, 1BR from AED 2.8M), JW Marriott Residences (WOW Resorts, Q4 2027, 1BR from AED 3.1M), Fairmont Residences (Ardee, Dec 2028), Jacob & Co Residences (Mantra, Jun 2028, 1BR from AED 2.1M)
Costa Mare and Playa Del Sol (Ellington, 2027–28), Shoreline (DAMAC, Q3 2028), W Residences (Q4 2028)
Pacific, Bab Al Bahr, Marjan Island Resort
Watch: Wynn slippage and cost overruns; a RAK supply wave peaking in 2028–29 (25,600–34,000 units by 2030); Al Marjan is 55% of RAK sale listings; delays at Nobu, W and Address; many newer developers with no delivery record.
Mina Al Arab · Hayat Island
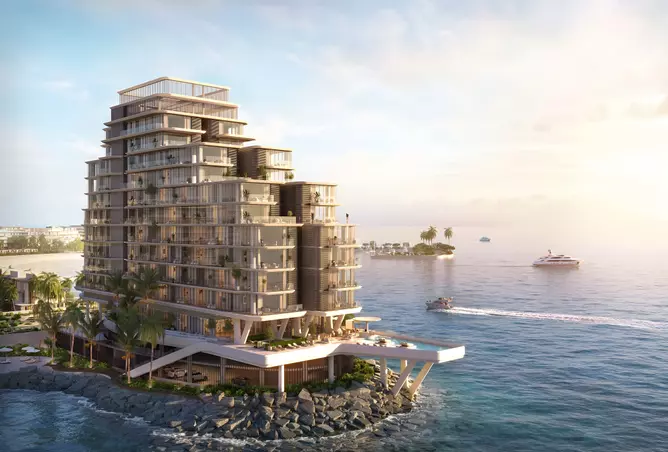
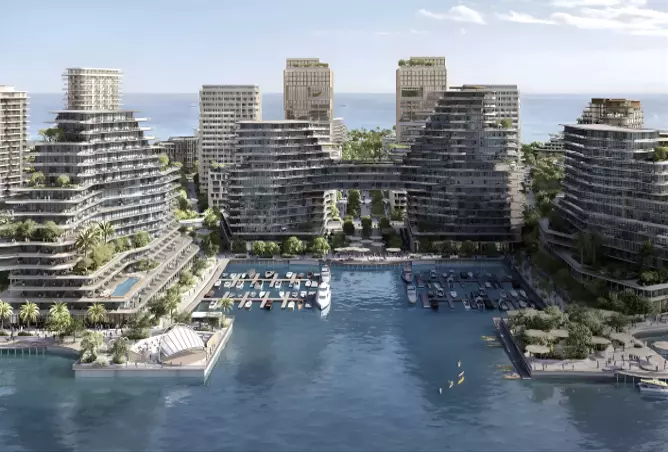
Capital growth
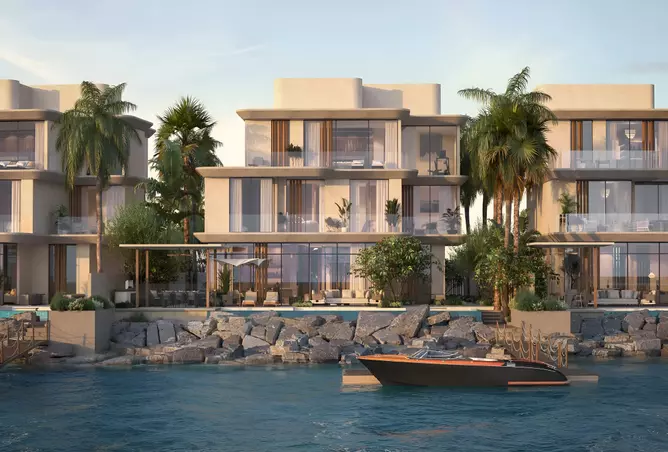
A family-oriented beach and lagoon community across the water from the Wynn, anchored by the Anantara and InterContinental hotels. It has lagged Al Marjan since 2025 and is now roughly flat (ValuStrat +2.3% YoY; asking −4%), so it is a cheaper way into the Wynn story.
Rental yield
Gross yields of about 4.5–5% (1BR ≈AED 60K). Rents had the best momentum in RAK in 2025 but have eased this year; Hayat Island beachfront units suit holiday lets.
Key projects
Anantara Mina Residences (Q2 2028, 1BR from AED 3.1M), Mirasol (Raha Island, Q1 2028, sold out) and Mirasol Phase 2 (Q3 2028, from AED 1.3M), Edge (Q2 2027, from AED 750K), SKAI (Q2 2028), Quattro Del Mar (Q2 2027), Nura (Q1 2029), Solera (Q2 2028)
Bay Residences, Bay Views, Gateway Residences, The Lagoons villas; Cape Hayat villas (Q4 2026)
Watch: RAK Properties' own pipeline; a back-loaded 1,400-unit handover target for 2026; asking prices softening.
Al Hamra Village

Capital growth
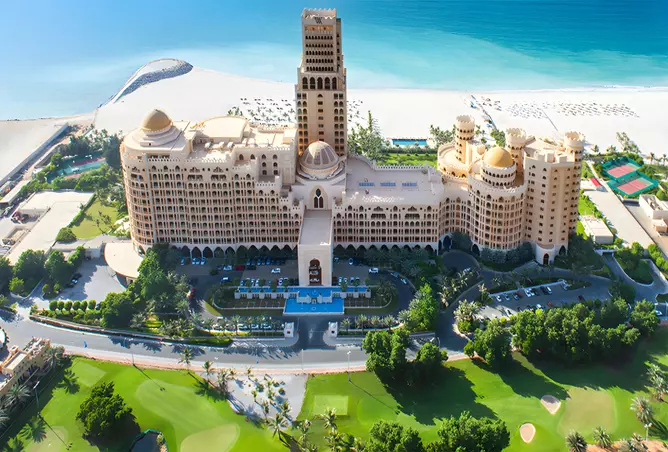
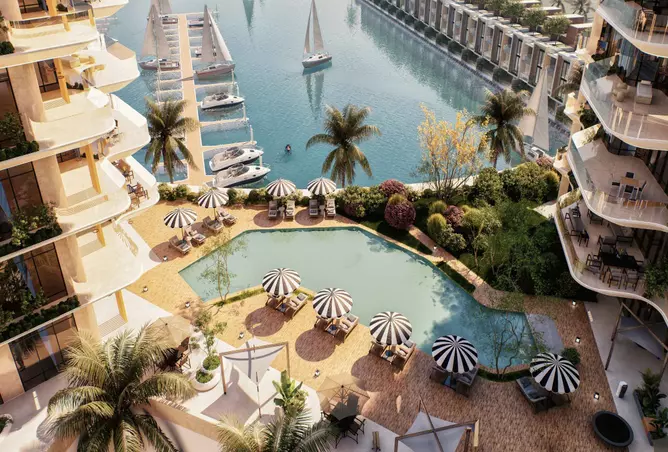
RAK's first freehold community — golf, marina and beach — and the cheapest beachfront entry in the emirate. Growth in 2026 is in the new waterfront and branded product: the Waldorf Astoria Sky Palace sold for AED 130M in January, a RAK record. Older stock is an income play rather than a growth play.
Rental yield
The best ready long-let yields in RAK at about 5.5–5.8% gross (1BR ≈AED 51K on ≈AED 0.8M), with stable rents and short-let demand from golf and beach guests.
Key projects
Waldorf Astoria Residences (Q1 2027, from AED 8.4M), Al Hamra Waterfront (Q1 2027, 1BR from AED 1.7M), Al Hamra Greens (Q1 2028, from AED 1.27M), Aila Homes (Q4 2028), Soto Grande (Ellington, Q4 2029, from AED 1.0M)
Royal Breeze, Golf Apartments, Bayti Homes, Falcon Island villas (sold out)
Watch: Ageing older stock; Al Hamra is one of the three biggest contributors to the RAK pipeline.
Sharjah
The best yields on the coast, with limited capital growth.
Sharjah's transaction value dipped in Q2 and recovered in Q3. Since 2022 all nationalities can own freehold in approved projects (52 so far). The beachfront is concentrated in Maryam Island (Al Khan), Sharjah Waterfront City and Al Mamzar, plus new east-coast resorts.
Maryam Island


Capital growth
Sharjah's established freehold beachfront island, open to all nationalities, at a 35–50% discount to Dubai beachfront. More than 3,000 units are 99% sold with over 1,200 handed over, and the 2025 launches sold out quickly. Upside is capped near term while Sharjah asking prices fall (−4.5% YoY) and the new phases hand over.
Rental yield
The highest established beachfront yields in this report: about 7–7.5% gross (1BR asking rent ≈AED 59K on ≈AED 0.78M). Rents are softening (−7% in six months; Al Khan 1BRs −15.6% QoQ in Q2), so underwrite 6.5–7%.
Key projects
Cyan, Sapphire, Azure and Indigo Beach Residences, Jawaher, Noor, Crystal
Topaz Residences (Q1 2027, from AED 0.97M), Citrine Residences (Q1 2027, from AED 0.97M), Layla Residences (Jan 2027, sold out), GEM Residences (Dec 2027, sold out), Anbar and Rehan (Q3 2026)
Watch: A 2026–27 handover wave; falling rents; off-plan flips on 10/20/70 plans adding resale supply.
Sharjah Waterfront City (Al Hamriyah)
Capital growth
A large island masterplan in the far north of Sharjah, about 40 minutes from Dubai, with low entry prices and big units. With 1,700+ resale listings and amenities still years away, expect flat to low single-digit growth.
Rental yield
About 6–7% gross on ready stock (Blue Bay Walk, Blue Beach), but the tenant pool is thinner than in Al Khan, so voids and furnishing costs bite.
Key projects
Sun Island, Blue Bay Walk, Blue Beach Residence
Blue Pearls, Al Thuraya Island, The View Island
Watch: Oversupply within the masterplan, a long build-out, a remote location and weak liquidity; confirm freehold status per project.
Al Mamzar & the Sharjah east coast

Capital growth
Al Mamzar is the Sharjah beachfront closest to Dubai and had the biggest asking-price rise in Sharjah in 2025 (+23%). Alef's AED 4bn Linar (2,620 units, 325 m of beach) had its first phase fully reserved in June 2026, after the conflict began. On the east coast, Khorfakkan Resort (573 freehold units) opened in May 2026 and Arada's Anantara Sharjah Residences is under way.
Rental yield
Not enough rent data to quote a yield. The east-coast projects are lifestyle and second-home plays.
Key projects
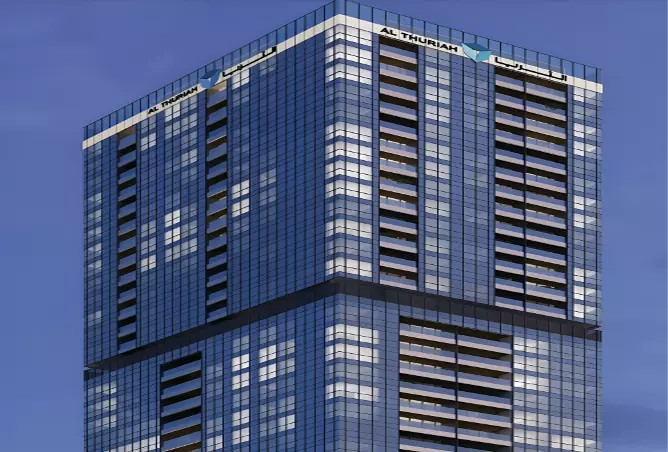
Linar (Alef, from AED 849K, Tower A from 2030), La Plage Tower 2 (Al Thuriah, from AED 540K)
Khorfakkan Resort (Asas, opened May 2026), Anantara Sharjah Residences (Arada, Al Heerah, ≈2027–28), Khor Kalba City (masterplan, launch targeted Dec 2026)
Watch: A long lock-up at Linar (2030); untested resale markets on the east coast.
Ajman
Cheap income, but the weakest market in 2026.
Ajman's volumes have fallen hardest of the three northern emirates this year. Foreigners can buy freehold in designated areas, including Al Zorah and the Corniche.
Al Zorah


Capital growth
Ajman's only premium beach-and-golf masterplan, priced at about twice the Ajman average, with a Four Seasons resort and a new AED 2.7bn Samana joint venture. Ajman volumes fell about 23% in the first nine months of 2026 and asking prices are about 10% lower than six months ago, so expect flat prices near term.
Rental yield
About 6–7% gross on ready stock (1BR ≈AED 76–89K), backed by beach and golf demand; the renter pool is narrow.
Key projects
Golf Estates, Seaside Hills (from AED 2.0M), Beach Hills Villas
Sealine Residence (Q4 2026, from AED 1.36M), Creekside Residence (Mar 2028, from AED 1.1M), Gateway Porto Al Zorah (Q4 2026), Golf View Living (Takmeel, Q2 2029, from AED 700K), Park Golf Views (Q3 2028), Sea Glints mansions (Solidere, Q4 2027), Samana JV (2,000+ units, pre-launch)
Watch: An off-plan pipeline from smaller developers; thin liquidity; Ajman volumes down in 2026.
Ajman Corniche
Capital growth
Commoditised high-rise stock with large units and the lowest beachfront entry price in the UAE. Sea views add little premium, and off-plan resales at Mawjan already trade near launch price, so appreciation is limited.
Rental yield
A deep, affordable tenant pool keeps occupancy high, but low rents (1BR ≈AED 34K) leave about 4–5% net after service charges.
Key projects
Mawjan Residence (Aqaar, Dec 2028, studios from AED 583K), Ajman One Phase 2 (Aqaar, Dec 2026), Amwaj Tower (Q4 2028), Bluebell Residence (GJ, from AED 496K)
Ajman Corniche Residence, Corniche Tower
Watch: Older buildings and service charges; little capital growth.
Umm Al Quwain
The most speculative segment: Sobha-dominated, with no resale or rental history yet.
UAQ's beachfront story is mostly Sobha's off-plan pipeline, priced like Dubai's mid-market, with the first handovers targeted for late 2027. Deyaar (Aya) and Citi Developers (Amra) are the main other developers, both in Al Raudah next to the Vida resort, and Amra's studios from about AED 690K are the cheapest beachfront ticket in the emirate.
Sobha Siniya Island


Capital growth
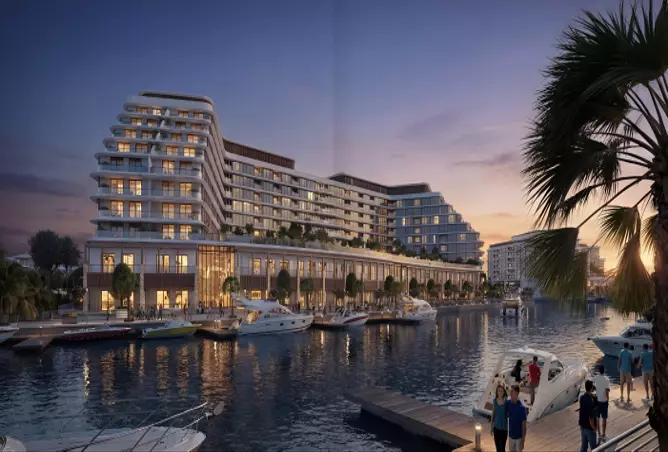
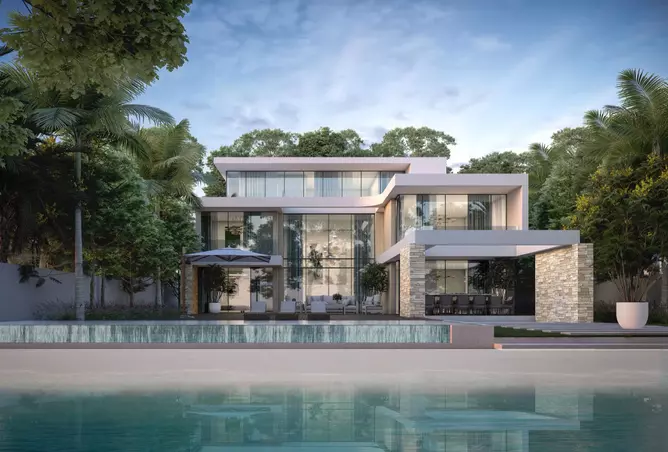
Sobha's US$5bn natural-island resort (about 8,000 units in phase 1) with 12 km of coastline and a bridge to the mainland. Sobha has sold about AED 8bn across its two UAQ projects, pricing each launch above the last. But that is launch-to-launch pricing by one developer with no resale data, at Dubai-level prices per sqft on very small 1BRs.
Rental yield
Unproven — there is no completed stock. In a weak tourism year, underwrite 5–6% gross at best.
Key projects
Selene Beach Residences (Q4 2027, sold out), Delphine Beach (Q4 2027, from AED 1.11M), Aquamarine Beach (Q2 2028), Coraline Beach (Q4 2028), Bayside and Pierside Marina (Q1 2029), Pristine Beach Residences (Q3 2029, from AED 1.43M), Capeside Marina Residences (Jun 2030, from AED 2.0M); villas from AED 10.6M (Q4 2028)
Watch: A Sobha-dominated market; untested handover dates; an isolated location (~50 minutes from Dubai); BirdLife named Al Siniyah a Key Biodiversity Area in Feb 2026; confirm freehold status in the SPA.
Downtown UAQ & Al Raudah


Capital growth
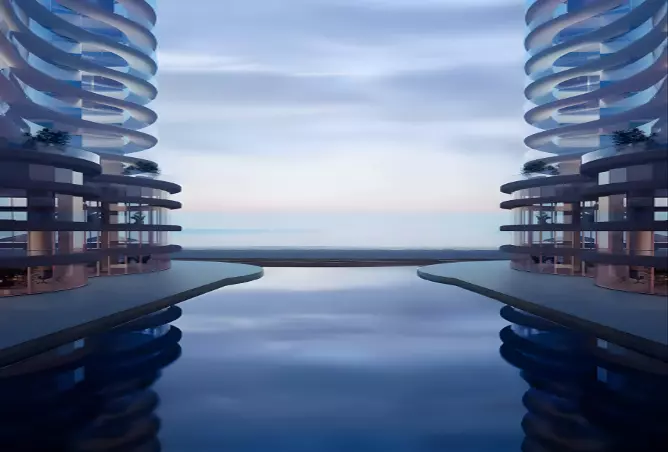
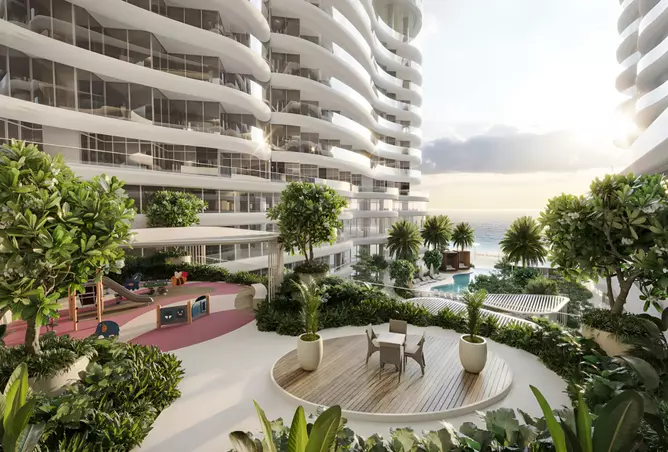
Sobha's 25m sqft mainland waterfront plan (11 km of coastline, 150,000 residents), cheaper per sqft than Siniya and with better road access; the first Aquamont towers were over half sold in a week. In Al Raudah, next to the Vida Umm Al Quwain resort, Deyaar's Aya Beachfront and Citi Developers' Amra (820 furnished, wellness-led serviced residences in three towers; studios from about AED 690–790K, construction started May 2026) offer the lowest beachfront entry tickets in UAQ. A 150,000-resident plan means a very long supply tail.
Rental yield
No completed stock and no rents yet. Amra plans to run a managed rental programme (12% management fee), so returns will depend on holiday-let demand in UAQ, which is unproven.
Key projects
Sobha Aquamont (Jun 2028, from AED 1.1M), Sobha AquaCrest (Jun 2029, from AED 1.17M)
Amra (Citi Developers, Q4 2028, studios from AED 690K, 1BR from AED 1.1M, 2BR from AED 1.6M; 70/30 plan with 30% over three years after handover), Amra Phase 2 (Q4 2029, from ≈AED 790K), Aya Beachfront Residences (Deyaar, Jun 2028, 1BR from AED 1.1M)
Watch: A very long supply tail; no UAQ transaction data is published; handover dates are already slipping (Aya); Citi Developers entered the UAE in late 2023 and we could not verify a completed UAE project, and Amra unit sizes are not yet published, so price per sqft cannot be checked.
Fujairah
A lifestyle and second-home market, not an investor market.
Freehold has historically been limited to UAE and GCC nationals (Eagle Hills' Address Residences Fujairah was sold on that basis), and we found no 2025–26 change to that rule. There is no public price index and only about 58 properties listed for sale emirate-wide, so we have not scored it.
The developers
On the beach, the developer matters as much as the location: delivery record, build quality and resale liquidity. Dots show our view of each developer's track record.
Dubai's strongest delivery record: 130,900+ units since 2002, a AED 164.9bn backlog (H1 2026), and the most liquid resale brand. Top developer by 2026 sales value. Its first RAK project was 18% built in July 2026, behind plan.
Master developer of the palms and Dubai Islands; delivered Palm Jumeirah, but stalled Palm Jebel Ali and Deira Islands after 2008. Over Dh13bn of Palm Jebel Ali contracts now awarded.
Low-rise, lifestyle-led, scarce supply. Strongest at the ultra-prime end (135 sales above AED 15M in 2026). Mostly delivered stock.
Ultra-luxury, Dorchester Collection partner; S&P-rated; the most AED 15M+ sales of any developer in 2026 (212). Delivered One at Palm.
Established Marina developer; 1,502 units delivered in 2026 so far. Peninsula handovers slipped slightly.
Builds in-house; S&P-rated; record 6,819 handovers targeted in 2026. Seahaven now looks like 2027; AED 8bn sold in UAQ, with no handovers there yet.
Design-led boutique quality; 5th by 2026 sales. Beach House delivered on the Palm in 2025; one of the three biggest contributors to the RAK pipeline.
2nd by 2026 sales volume; S&P-rated. Some Dubai Harbour units already resell below the original price.
Ultra-prime branded specialist; set the Dh422M record at Aman Residences.
Omniyat's newer brand for upper-premium design-led product; Hado sold out at launch. No completed Beyond building yet, but backed by Omniyat's delivery record.
Mid-market volume developers concentrated on Dubai Islands; more variable delivery records — check each project.
Abu Dhabi's state-linked master developer and the benchmark for delivery; AED 71.6bn backlog. H1 2026 UAE sales fell 46% on a "measured approach" to launches.
Record launches (≈AED 13bn of Hudayriyat Golf Estates in days), but its residential delivery record is unproven — first handovers from Q4 2026.
Delivered Maryam Island (over 1,200 units handed over, 99% sold) and Address Fujairah; Ramhan's first phase is due Q4 2026.
ADX-listed, the largest local builder in RAK; 264 handovers in H1 2026 against a 1,400 target, so H2 is back-loaded.
Long delivery record in RAK and holder of the emirate's price record (AED 130M Waldorf Sky Palace).
Ajman Government and Solidere joint venture; slow but delivered (Golf Estates, Seaside Hills). Gateway Porto slipped from 2025 to 2026.
Delivered Sun Island and Blue Bay Walk phases, but carries large unsold and resale stock in its own masterplan.
Strong branded launches on Al Marjan, but no verified delivery record yet — weigh the developer as much as the brand.
Sources and notes
- Metropolitan Premium Properties (DLD-based resale reports): Palm Jumeirah, Dubai Harbour, JBR, Bluewaters, La Mer, Dubai Marina — H1 and Q3 2026.
- ValuStrat VPI (Jun–Aug 2026) via Khaleej Times and Zawya; Cavendish Maxwell (Aug and Q3 2026); Savills (Q2–Q3 2026); CBRE and Cushman & Wakefield (Q2 2026); Knight Frank (Jul 2026); S&P (Oct 2026).
- Huspy Palm Jebel Ali H1 2026 report (Property Monitor data); Nakheel press releases (Jun, Aug 2026); The National (Jun, Oct 2026).
- betterhomes area guides and Dubai Islands report (Aug 2026); fäm Properties (Jul 2026); Bayut/dubizzle H1 2026 (asking prices); Morgan's International Realty branded residences report (H1 2026).
- Investment Map (investmentmap.ai) — DLD-based area data for sales, average price, resale price change, rental yield, listings and units under construction (1-year view, Apr 2025–Apr 2026).
- Dubai Department of Economy and Tourism arrivals (Jan–Aug 2026); Property Finder new-project pages for project details and images.
- Figures differ between sources by 10–30% depending on method (resale vs combined, mean vs median, asking vs transacted). Yields are gross and indicative; this report is for discussion and is not a valuation.
- Abu Dhabi: ADREC (2025 annual, Feb 2026; H1 2026, Jul 2026; Jan–Sep 2026 via IndexBox, Oct 2026); ValuStrat Abu Dhabi Q2 2026; Cushman & Wakefield, CBRE, JLL and Knight Frank Q2 2026; Cavendish Maxwell H1 2026; Projectory and ADX Interact (ADREC-based, Aug–Oct 2026); Bayut H1 2026 sales and rental reports and price indices (Sep 2026); Aldar H1 2026 results; DCT via Skift (Sep 2026).
- Ras Al Khaimah: CBRE RAK H1 2026 review (Sep 2026); Cavendish Maxwell (Apr, Jul, Sep 2026); ValuStrat RAK Q1–Q2 2026; RAK Municipality via WAM (Aug 2026); Wynn Q2 2026 earnings via The National and Skift (Aug 2026); Fitch (Oct 2026); RAK Properties H1 2026 results; Bayut price indices (Jul–Sep 2026).
- Sharjah, Ajman and Umm Al Quwain: Sharjah Real Estate Registration Department (H1 and 9M 2026); Cavendish Maxwell (Jun 2026); Colliers Q2 2026 (Aug 2026); Ajman land department via WAM (2025–Oct 2026); Bayut indices, listings and 2025 market reports; betterhomes (Mar 2026); Alef Group Linar release (Jun 2026); Sobha Realty (Jan 2026); Cresco Siniya guide (Aug 2026); Amra by Citi Developers via Property Finder project page (Oct 2026), Alnair (Apr 2026) and Khaleej Times (Nov 2023).
- Outside Dubai there is no open, DLD-style transaction register at community level, so most northern-emirate prices, rents and yields are asking-price based. Treat them as indicative; in RAK, valuation indices (ValuStrat, Property Monitor) for ready stock run well below asking indices skewed by new branded launches.